Two commodities, one balance sheet, two completely different stories. That is the real signal inside Rio Tinto's latest operational update, which showed copper output held steady while iron ore shipments pushed higher. Read as a single data point it looks like routine mining-house housekeeping. Read as a structural statement, it is a map of where supply can and cannot respond to price.
Rio Tinto is the world's largest Pilbara iron ore shipper and one of the industry's most important copper producers, through its majority stake in the Oyu Tolgoi underground mine in Mongolia, the Kennecott operation in Utah, and a 30% holding in Escondida in Chile, the largest copper mine on the planet. When the company reports iron ore volumes rising while copper output stays flat, it is not describing two product lines. It is describing two different physics of supply.
The mechanism: elastic rock versus inelastic rock
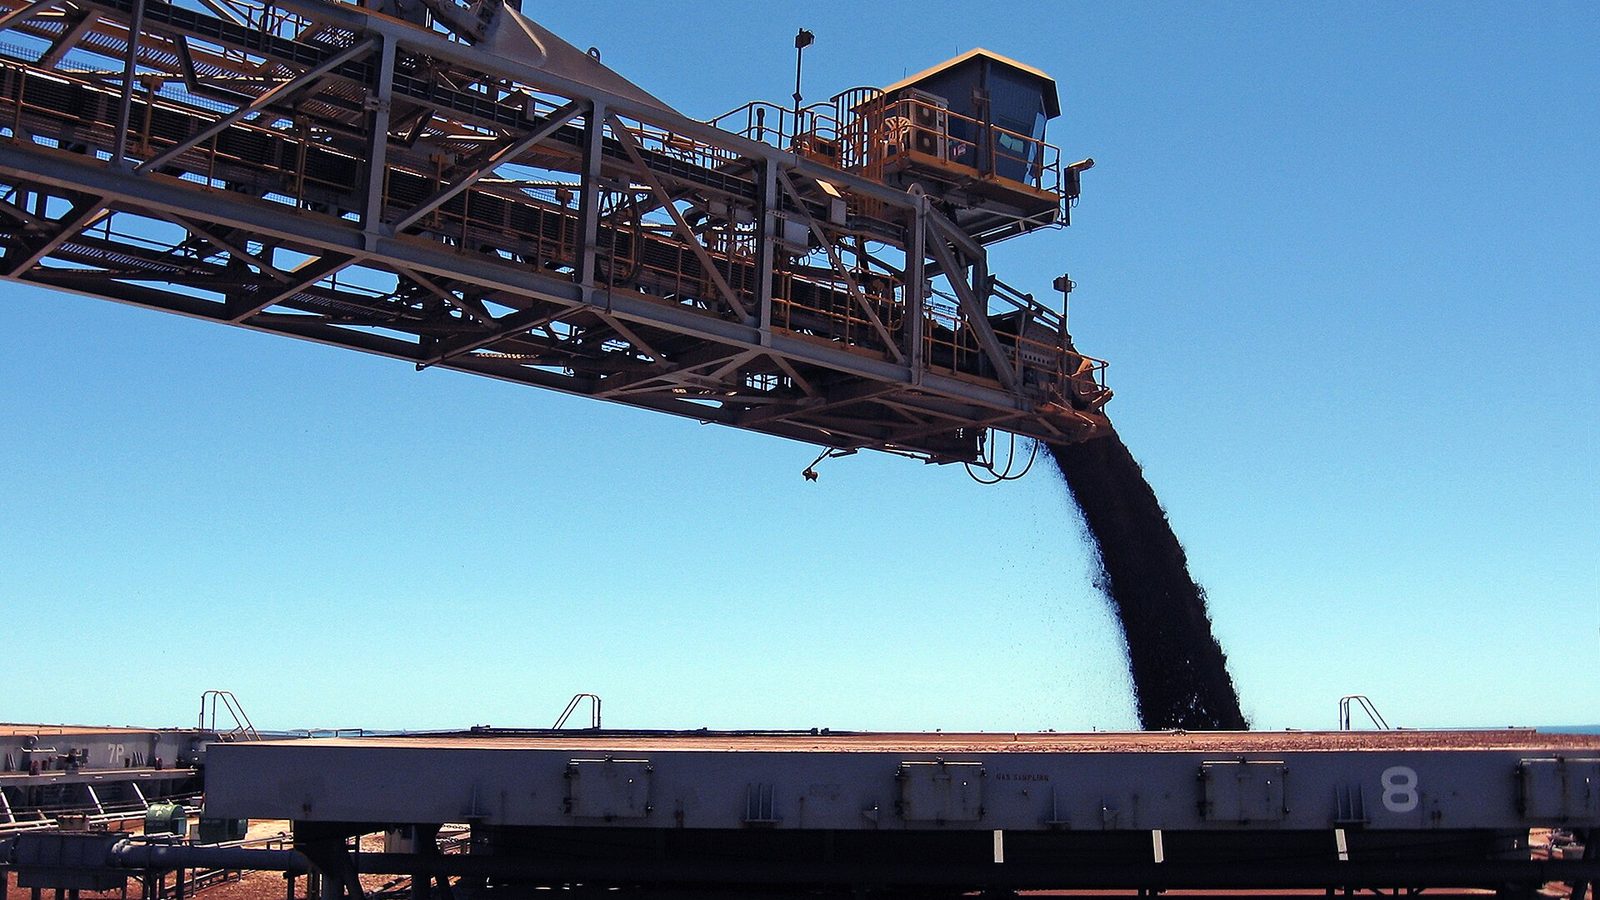
Pilbara iron ore is, in supply terms, an elastic system. The rail, port and mine infrastructure is built, depreciated and running. Lifting shipment volumes a few percentage points is a scheduling and blending decision, not a capital decision. Iron ore supply can flex up or down inside a year because the fixed costs are already sunk and the incremental tonne is cheap to produce and easy to move.
Copper is the opposite. Oyu Tolgoi's transition to underground block caving took more than a decade and billions of dollars of capital before it produced a tonne of incremental copper. Ore grades at legacy copper mines are declining globally, and a new mine, once permitted, typically takes most of a decade to reach first production. Copper supply cannot flex to meet a price signal in the way iron ore can. That is why copper output can be reported as merely steady even as copper prices sit near multi year highs on electrification and grid demand. Flat is not a failure of execution. Flat is close to the physical ceiling.
The second order effect: the complex is bifurcating in real time
This is the part that matters for positioning, and it is the read Komey Tetteh keeps coming back to across the mining complex this year. Iron ore remains tethered to the old rhythm: Chinese steel output, property construction, infrastructure stimulus. It is a volume and China-cycle trade, and Rio Tinto's ability to raise shipments on demand confirms that the supply side of that market is still doing exactly what it has always done, responding to orders.
Copper has decoupled from that rhythm. Demand for copper is no longer just an industrial cycle variable; it is a structural call on grid buildout, renewables interconnection and the power infrastructure behind data center expansion. Supply, meanwhile, is capacity constrained almost regardless of price, because the lead time on a new mine is measured in years, not quarters. A major producer holding copper output flat while pushing iron ore volumes higher is not a company choosing one commodity over another. It is a company showing you, in the same release, which of its two main markets can absorb a demand shock and which one cannot.
From a volatility desk's perspective, this is a convexity story before it is a price story. A market where supply cannot respond to demand is a market where small demand surprises produce disproportionate price moves, and where the options surface tends to underprice tail risk because realized volatility has been muted by years of range-bound trading. A delta-neutral book running SPX and ES exposure does not take a directional view on copper. It reads this kind of supply asymmetry as a signal to watch cross-asset correlation: copper has historically been treated as a macro growth barometer, and if its supply curve is now structurally steeper than iron ore's, its price behavior under stress will increasingly diverge from the broader commodity complex, which matters for how correlation assumptions get built into cross-asset hedges.
The honest counter-case
This thesis breaks if copper supply turns out to be more elastic than it looks. Scrap recycling flows can expand faster than mine supply when prices rise, and substitution toward aluminum in some grid and wiring applications has historically capped copper demand growth before it reaches the ceiling the bull case assumes. It is also possible that a slowdown in Chinese construction drags iron ore volumes down hard enough that the entire framing reverses: a soft China print would hit the elastic commodity harder and faster than the inelastic one, and a single quarter of flat copper output tells you nothing about whether that ceiling is permanent or just this year's capital expenditure cycle catching up.
What I am watching next is simple: whether other major copper producers report the same pattern, flat to lower output despite high prices, because one company's numbers are an anecdote and three companies' numbers are a supply curve. I am also watching Chinese steel margins, because if they stay compressed even as shipment volumes rise, the iron ore side of this trade is running on inventory restocking rather than genuine demand.
If copper supply really cannot respond to price the way iron ore can, what does that do to every cross-asset hedge that still assumes commodities move together?
Common questions
Why did Rio Tinto's copper production stay flat while iron ore shipments rose?
Iron ore supply from Rio Tinto's Pilbara operations runs through mature, depreciated rail and port infrastructure, so shipment volumes can be adjusted within a year through scheduling and blending. Copper supply depends on long-lead capital projects like Oyu Tolgoi's underground expansion and on declining ore grades at legacy mines, so output cannot flex nearly as quickly even when prices are elevated.
What is Oyu Tolgoi and why does it matter for copper supply?
Oyu Tolgoi is Rio Tinto's underground block cave copper and gold mine in Mongolia, developed over more than a decade at a cost of billions of dollars. It is one of the company's main sources of copper growth, and its long development timeline illustrates why new copper supply cannot respond quickly to rising demand.
Does rising iron ore supply mean Chinese demand is strong?
Not necessarily. Rising shipment volumes show that producers can supply more tonnes when ordered to, since Pilbara infrastructure has spare capacity to flex. It does not by itself confirm the strength of underlying Chinese steel or construction demand, which is a separate question worth tracking through steel margins and inventory data.
Why is copper demand described as structural rather than cyclical?
Copper demand is increasingly tied to grid buildout, renewable energy interconnection and power infrastructure for data centers, uses that are less tied to the traditional industrial and construction cycle than iron ore demand is. This shift is why copper's demand profile is behaving differently from iron ore even within the same mining company's output.
What would prove this copper supply constraint thesis wrong?
The thesis weakens if scrap recycling expands fast enough to offset mine supply limits, or if industrial users substitute toward aluminum in wiring and grid applications, both of which have historically capped copper demand growth. A sharp slowdown in Chinese construction could also hit iron ore harder than copper, reversing the framing entirely.