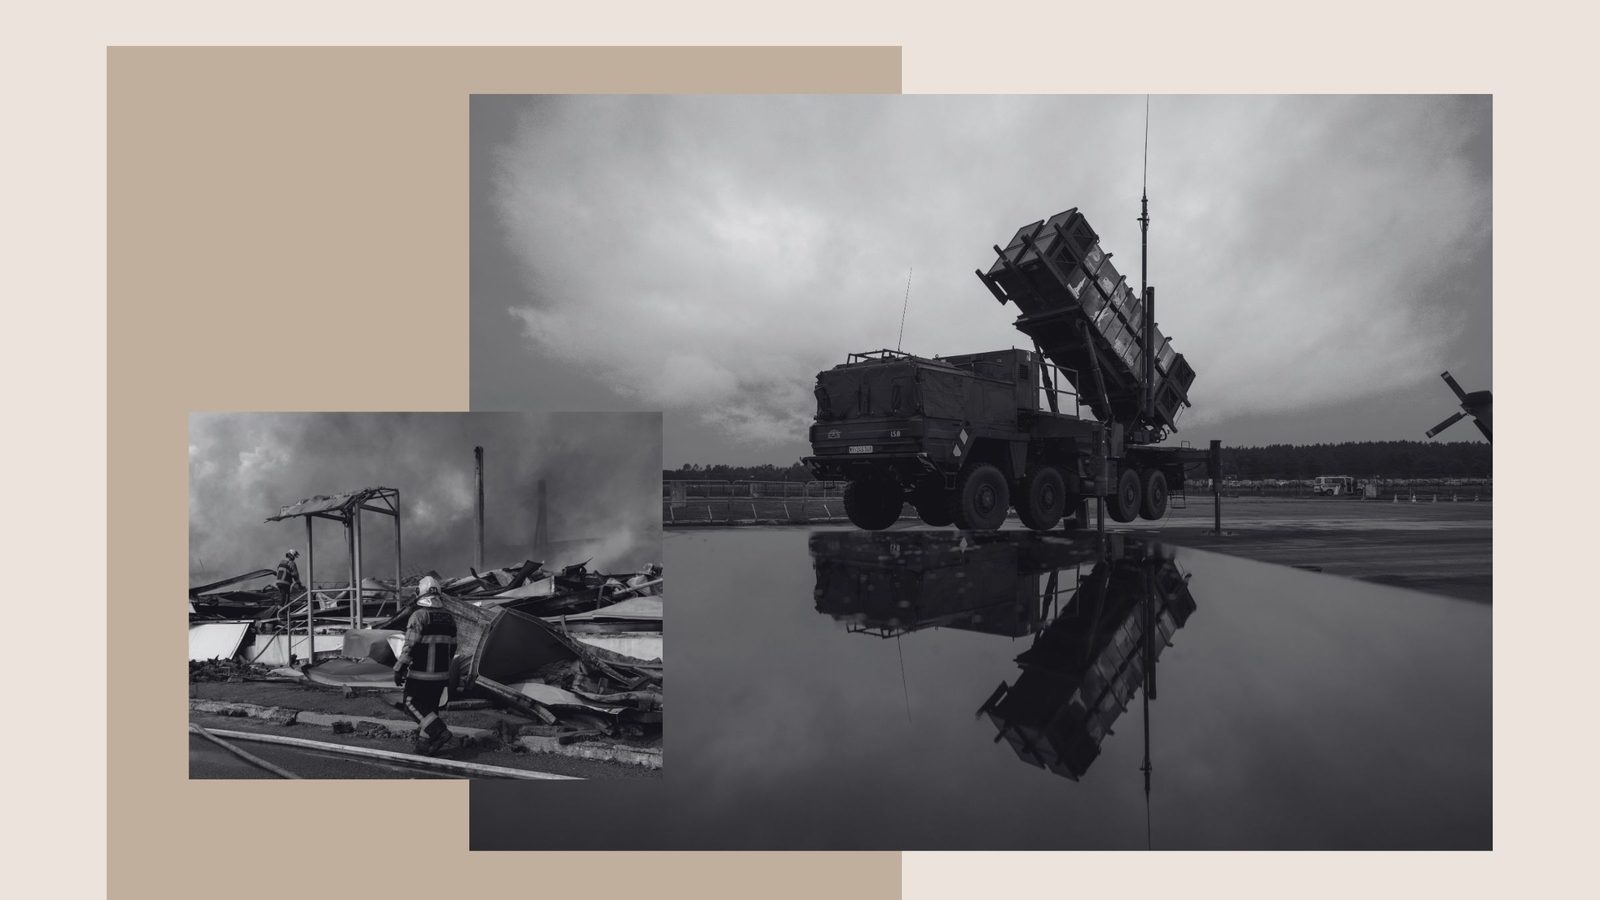
The United States spends more on defense than the next ten countries combined, yet active-duty recruitment is at its lowest level since the all-volunteer force was established in 1973, critical munitions stockpiles are depleted from Ukraine aid transfers, and the Navy cannot maintain its 355-ship target. The $886 billion fiscal year 2024 defense budget is the largest in American history in nominal terms, and it is simultaneously not enough to fund the military posture Washington's foreign policy demands. That contradiction is not a budgeting error. It is a structural feature of how American defense spending actually works, and the fiscal, monetary, and geopolitical second-order effects flowing from it are among the most mispriced macro variables in markets right now.
Where the Money Actually Goes: The Readiness vs. Modernization Trap
Of the $886 billion appropriated for fiscal year 2024, roughly 25 percent goes directly to personnel costs, including pay, healthcare, and retirement benefits for active, reserve, and retired service members. Another significant slice covers operations and maintenance, keeping aging platforms functional rather than replacing them. The Congressional Budget Office estimated in 2023 that the Pentagon's 30-year shipbuilding plan would require average annual expenditures of $40 billion, approximately 70 percent above the historical average, simply to reach and sustain a 355-ship Navy. The budget number sounds enormous until you see where it bleeds out.
The readiness trap works like this: deferred modernization in the 1990s post-Cold War drawdown, the so-called 'procurement holiday,' created a bow wave of recapitalization costs that is cresting right now. The Air Force's average aircraft age is over 30 years. The B-52 bomber, designed in the early 1950s, will likely remain in service through 2050. Keeping vintage platforms airworthy consumes maintenance dollars that could fund next-generation procurement, which in turn delays replacement, which increases maintenance costs further. This compounding dynamic is the central reason the defense paradox persists regardless of topline budget size.
The defense budget paradox is not a number problem. It is a structural problem, and structural problems do not resolve themselves in a single appropriations cycle. The capital allocation implications run for a decade.
The Fiscal Plumbing: How Defense Spending Flows Into Bond Markets
Defense is the one major spending category where Congress and the White House have shown bipartisan willingness to exceed the caps imposed by fiscal frameworks. The Fiscal Responsibility Act of 2023 nominally constrained discretionary spending, but defense appropriations consistently find a path through emergency supplementals, as the $95 billion Ukraine, Israel, and Taiwan supplemental passed in April 2024 demonstrated. That bill was not offset by revenue increases or cuts elsewhere. It was pure deficit spending, added directly to Treasury issuance.
The Treasury Department issued a net $2.4 trillion in new debt in fiscal year 2023, and defense supplementals are a structurally recurring component of that supply. When the bond market absorbs additional supply against a backdrop of the Federal Reserve no longer being a price-insensitive buyer through quantitative easing, the price of duration rises and yields move higher. The 10-year Treasury yield breaching 5 percent in October 2023 for the first time since 2007 coincided precisely with peak anxiety about deficit-financed government spending, of which defense supplementals were a visible catalyst. The defense paradox is therefore not just a military problem. It is a duration problem baked into the structure of the bond market.
Industrial Base Fragility and the Single-Source Premium
The most consequential result of the defense spending paradox is the atrophy of the defense industrial base during the post-Cold War period. Between 1990 and 2000, the number of prime defense contractors consolidated from 51 to 5 through a wave of mergers explicitly encouraged by the Pentagon in what became known as the 'Last Supper' meeting in 1993. Today, for critical systems like nuclear submarines, solid rocket motors, and certain classes of precision munitions, there is effectively a single supplier. Lockheed Martin, RTX Corporation, Northrop Grumman, General Dynamics, and L3Harris Technologies collectively capture the vast majority of prime contract value.
Single-source dependency creates pricing power that persists regardless of budget topline. The Army's recent contract modifications for 155mm artillery shells, the very rounds being consumed at scale in Ukraine, revealed that expanding domestic production requires multiyear fixed-price commitments to justify contractor capital investment. The Pentagon's own Defense Industrial Base report from 2022 flagged that the U.S. could sustain high-intensity conflict munitions consumption for only weeks before running critical shortfalls. Replenishment timelines are measured in years, not months. That structural bottleneck means incremental defense budget dollars are increasingly captured by a small number of publicly traded primes, making the earnings stream for this cohort unusually durable and politically protected.
Global Macro Ripple: NATO Burden-Sharing and the European Rearmament Trade
Washington's defense paradox is directly accelerating one of the most significant capital reallocation stories in European equity markets in a generation. The political pressure on NATO allies to meet and exceed the 2 percent of GDP defense spending target, amplified dramatically by the Ukraine conflict and U.S. political signals about alliance reliability, is translating into concrete procurement budgets. Germany's Zeitenwende, the historic pivot in defense policy announced in February 2022, committed a 100 billion euro special defense fund. Poland is targeting 4 percent of GDP in defense spending, the highest in the alliance. Romania, the Netherlands, and the Baltic states are all accelerating procurement timelines.
The beneficiaries of European rearmament are partially American primes, given NATO interoperability requirements that favor F-35s, Patriot systems, and HIMARS, but European champions like Rheinmetall, BAE Systems, Leonardo, and Thales are capturing an increasing share of domestic procurement. Rheinmetall's stock appreciated over 700 percent between January 2022 and mid-2024 as its order backlog swelled past 35 billion euros. This is not a speculative trade on geopolitical fear. It is a straightforward reflection of governments signing multi-year contracts, creating locked-in revenue visibility that equity markets are correctly capitalizing. The macro read is that European defense is in the early innings of a sustained procurement cycle, the kind that historically lasts a decade or more once it begins.
The Volatility Surface Tells a Story: How the Desk Positions Around Defense Shocks
From a delta-neutral volatility perspective, defense-adjacent macro events create a specific and recurring pattern in the options market. When geopolitical escalation drives sudden demand for exposure to defense primes, implied volatility on individual names like LMT, NOC, and RTX tends to spike sharply and then mean-revert as the news cycle digests. The gap between the implied move and the realized move in these names following major geopolitical events, the Russia-Ukraine invasion in February 2022, the October 7 Hamas attack in 2023, and the Taiwan Strait tensions of 2022, has consistently favored sellers of short-dated volatility, confirming that the fundamental demand shift for defense spending is secular rather than episodic.
The framework is to distinguish between volatility that reflects genuine uncertainty about outcomes versus volatility that reflects the market repricing a known structural shift. The defense spending paradox is the latter. The direction of defense budgets, both in the U.S. and across NATO, is not uncertain. The political economy makes sustained real increases in defense appropriations near-certain over the next decade regardless of which party holds power in Washington. What remains uncertain is the timing of specific contract awards, the path of Congressional appropriations battles, and the resolution of specific geopolitical triggers. Those timing uncertainties create options premium worth harvesting on defense sector ETFs like ITA and XAR, particularly in the 45 to 60-day tenor where event-driven vol tends to overshoot realized volatility by a measurable margin.
Second and Third-Order Effects: What Reprices Next
The first-order effect of rising defense budgets is visible: defense prime contractors reprice higher as earnings visibility improves. The second-order effects are less obvious but equally significant. Aerospace subcomponents suppliers, companies that manufacture titanium forgings, advanced electronics, propulsion systems, and composite materials, are capacity-constrained in ways the primes are not. TransDigm Group, a serial acquirer of sole-source aerospace components businesses, operates with EBITDA margins above 50 percent precisely because its parts have no substitutes. The defense procurement surge flows downstream to these suppliers with a 12 to 24-month lag, creating a second wave of earnings revisions that has not yet been fully reflected in valuations.
The third-order effect operates through the labor market and regional economies. Major defense production facilities are concentrated in specific congressional districts, Virginia, Connecticut, Mississippi, and Texas carry disproportionate defense employment, creating a political feedback loop that reinforces budget protection. More importantly for macro, defense employment is high-wage manufacturing work. The re-expansion of defense production capacity, including the planned expansion of submarine production at Huntington Ingalls and General Dynamics' Electric Boat facilities in Groton, Connecticut, represents a genuine reshoring of advanced manufacturing that competes with civilian aerospace and semiconductor manufacturing for the same skilled workforce, creating upward wage pressure in specialized technical labor markets that feeds into broader services inflation.
The American defense spending paradox resolves in only one direction over the medium term: more money, spread across a longer timeline, flowing through a concentrated industrial base with pricing power. The fiscal consequence is structurally wider deficits, persistent Treasury supply, and upward pressure on the term premium in long-duration bonds. The equity consequence is a sustained earnings upgrade cycle for defense primes and their subcomponent suppliers, with European champions participating fully given the NATO rearmament imperative. The volatility consequence, and this is where the desk's positioning is most active, is that episodic geopolitical shocks will continue to spike implied volatility on defense-sector names well above what realized volatility justifies, creating recurring opportunities in the options market for disciplined premium sellers with a clear view of the secular trend. The key risk to monitor is a negotiated resolution to the Ukraine conflict that removes the political urgency driving supplemental appropriations, but even that scenario delays rather than reverses the structural capex cycle already locked in by multi-year contracts and allied procurement commitments. Position accordingly.