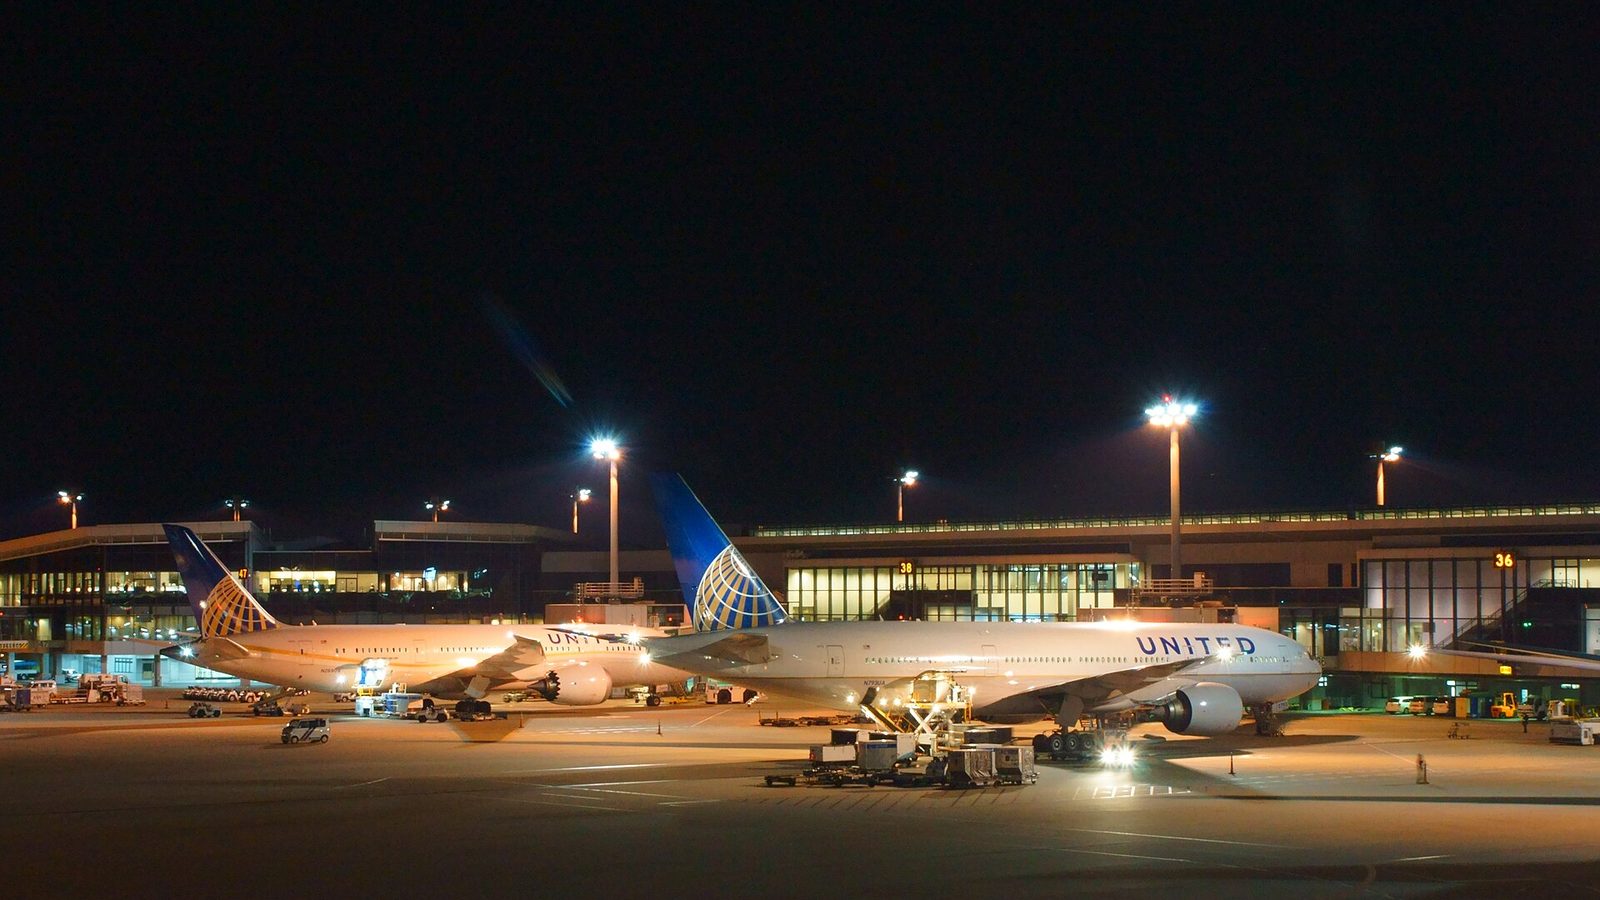
This is a refining margin story wearing an oil price costume. United Airlines posted record quarterly revenue and still gutted its full year profit guidance, and the gap between those two facts is where the real information sits.
United reported third quarter 2026 revenue of $17.88 billion, up 17% year over year and an all time high for the company. Adjusted earnings per share came in at $2.54, a few cents below the roughly $2.57 to $2.60 analysts expected. The company then cut its outlook hard: having guided in July to full year adjusted earnings of $9 to $11 a share, United now expects fourth quarter adjusted earnings of only 50 cents to $1.50 a share, which caps the full year figure near $7.22 at the high end. Fuel expense in the quarter rose 62% year over year to $4.84 billion.
The mechanism: this is not a crude oil problem
Jet fuel has two components. There is the crude oil price, which trades in one of the deepest, most liquid derivatives markets in the world. And there is the crack spread, the margin a refiner earns for turning crude into finished jet fuel. That spread is thinner, less liquid, and far more sensitive to physical bottlenecks than crude itself.
In 2026 that spread blew out to roughly $57 a barrel, a historic high against a more typical range closer to $15 to $20. The trigger was the closure of the Strait of Hormuz in late February, which removed a meaningful share of global crude supply and, more importantly, disrupted refined product flows at the same time. Jet fuel for the year is tracking near $152 a barrel, up almost 70% from 2025, and the industry's own fuel bill is projected to climb from $252 billion to $350 billion.
Airlines hedge against this exposure, but imperfectly. The industry hedge ratio for 2026 sits around one third, and most of that hedging is written against crude oil because that market is liquid and cheap to trade. The crack spread itself is rarely hedged with the same depth. That leaves airlines long exactly the part of the fuel price that just moved the most.
The second order effect
United's own numbers prove the point. Revenue accelerated. Passenger counts rose. Unit revenue growth was the best since before the pandemic. None of that showed up in the earnings miss or the guidance cut, because none of it was the problem. The problem sat entirely in cost of goods, specifically a input cost that trades in a market most hedging programs do not fully reach.
For anyone running cross asset exposure, that decoupling matters. Watching crude oil and assuming it tells you the airline cost story is watching the wrong instrument. Crude can sit flat while the crack spread does the damage, and crude can fall while jet fuel barely moves if refining capacity stays tight. A delta-neutral book built around energy and transport volatility has to treat the crack spread as its own underlying, with its own term structure and its own basis risk against whatever crude hedge sits next to it. That basis is precisely the kind of dislocation a volatility desk is built to isolate rather than guess at.
The headline number is the oil price. The number that actually moved United's income statement is the crack spread, a thinner and far less liquid market that most hedging books barely touch.
The honest counter-case
If Hormuz related disruptions ease and refining capacity comes back online faster than crude production itself normalizes, the crack spread can compress quickly, since it is a physical bottleneck problem rather than a reserve or production capacity problem. United's own disclosures noted it would sit above the high end of its earnings guidance range if fuel prices returned to early July levels. That means the current earnings compression could prove more temporary than the guidance cut implies, and 2027 estimates built on today's crack spread may turn out too conservative rather than too aggressive. The counter-case is not that the fuel shock was overstated. It is that refining bottlenecks, unlike crude supply shocks, tend to resolve faster than markets initially price.
What we are watching next is the crack spread term structure itself, not the crude oil headline. Jet fuel crack futures several quarters out will tell you whether the market expects this refining squeeze to persist into 2027 or fade as capacity adjusts. Komey Tetteh is tracking that curve alongside airline equity implied volatility, because the two should move together and any divergence is where the next mispricing shows up. If your own fuel cost assumptions still run through the crude oil price alone, ask what spread is actually sitting inside that number.
Common questions
Why did United Airlines miss earnings estimates in the third quarter of 2026?
United reported adjusted earnings per share of $2.54, just below the roughly $2.57 to $2.60 analysts expected, even as revenue hit a record $17.88 billion, up 17% year over year. The miss came entirely from the cost side: fuel expense rose 62% year over year to $4.84 billion in the quarter.
What is the jet fuel crack spread and why does it matter for airline stocks?
The crack spread is the price difference between crude oil and refined jet fuel, effectively the refiner's margin for turning oil into usable aircraft fuel. In 2026 that spread reached roughly $57 a barrel, a historic high, compared with a more typical $15 to $20 range, which means jet fuel costs can rise far faster than crude oil itself when refining capacity is constrained.
Did United Airlines cut its full year 2026 profit guidance?
Yes. United had guided to full year adjusted earnings of $9 to $11 per share in July. After the third quarter report, with fourth quarter adjusted guidance of 50 cents to $1.50 per share, the top end of the full year range fell to about $7.22 per share.
Is United Airlines the only airline facing higher fuel costs in 2026?
No. Delta, American, Alaska, JetBlue and several European carriers have all revised 2026 fuel expense estimates sharply higher following the disruption to crude and refined product supply that began in late February 2026, with industry wide fuel costs projected to rise from $252 billion in 2025 to $350 billion in 2026.
What caused jet fuel prices to spike in 2026?
A closure of the Strait of Hormuz in late February 2026 removed a significant share of global crude oil and refined product supply, pushing both crude prices and refining margins sharply higher. Jet fuel prices for the year are projected to average around $152 a barrel, nearly 70% above 2025 levels.
Do airlines hedge against jet fuel price increases?
Airlines typically hedge a portion of their fuel exposure, with the industry hedge ratio sitting at roughly one third for 2026. Most of that hedging is done against crude oil, which trades in a deep liquid market, leaving the refining margin itself largely unhedged and exposed to sudden spikes.