The bond market is telling two different stories at once, and one of them is about to be proven wrong. Rate volatility is spiking. Corporate credit spreads are not. That gap does not stay open. It closes, and it closes fast, usually in the direction nobody positioned for.
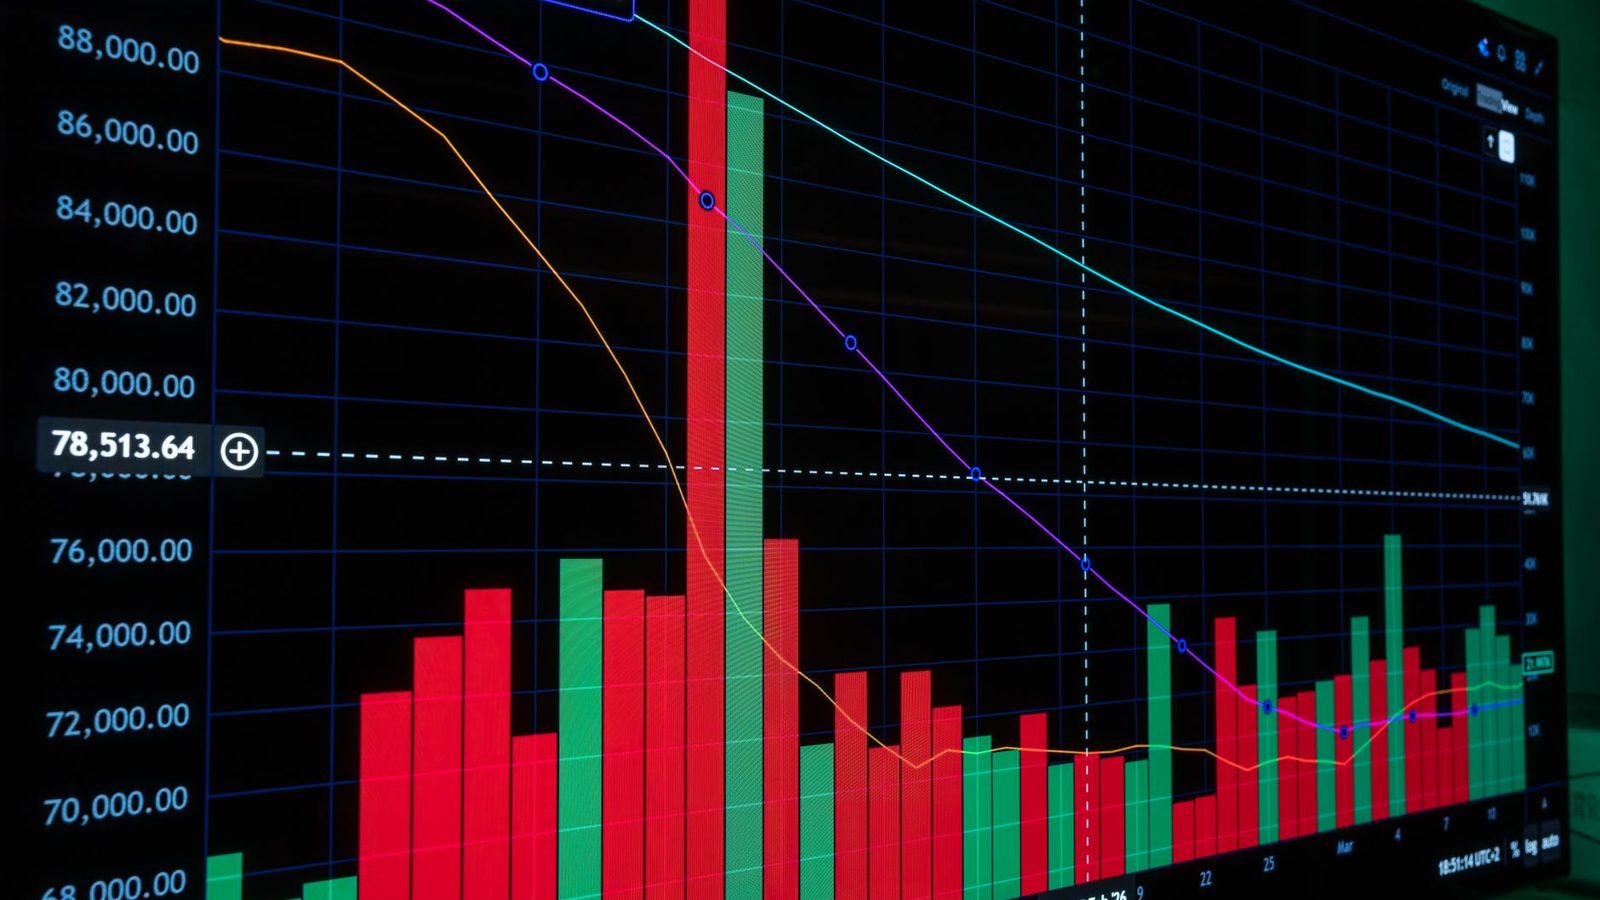
Corporate bonds have been relatively resilient amid a global government bond selloff, but the strength may not last. Bond market volatility, a measure of uncertainty about the direction of bond yields, is spiking, while investment grade credit has held its ground with spreads on the original report US Corporate Bond Index sitting near 75 basis points. That is the setup. Yields are being repriced with real uncertainty about where they land next, yet the market that funds corporate America is acting as if none of that uncertainty matters to it.
It does matter. It always has. Historically, elevated bond volatility has foreshadowed trouble for corporate debt, as nervous retail investors and others pull money from the market. The mechanism is not complicated once you strip out the jargon. Rate volatility moves first because it is priced in liquid, exchange-traded instruments that react within minutes. Credit spreads move second because they depend on an actual seller showing up in a bond that trades by appointment, not by the click of a button. Retail investors in bond funds do not watch the MOVE index. They watch their account balance. When volatility bleeds into daily statement value, redemptions follow, and redemptions force fund managers to sell whatever is liquid enough to sell, which in a stressed tape is rarely the bond that most needs to reprice. It is the good name sold to raise cash, which is precisely how contagion spreads through credit without a single default occurring.
The part almost nobody is discussing is what happens underneath investment grade, in the marks that do not update in real time. Rating agencies are already showing far more downgrades than upgrades across the corporate universe, a signal that credit quality has been quietly deteriorating well before any spread widening shows up in the index level. Layer onto that the volume of recent borrowing tied to speculative artificial intelligence buildouts, financed at rates roughly double where they sat a few years ago, and you have a stock of debt that is more sensitive to a volatility shock than the headline spread number suggests. Private credit vehicles and CLO structures mark their holdings on a lag. They will not move on day one of a volatility spike. They will move on day thirty, after the retail redemption wave has already forced public market spreads wider and dragged the slower-marked private book down with it, whether or not the underlying credit has actually changed. That lagged repricing is the second-order effect. It is not priced because it cannot be observed yet.
The honest counter case
This does not have to resolve the way the pattern suggests. Heavy corporate issuance since Labor Day has still found buyers, and demand has absorbed supply without spreads cracking, which tells you real money accounts still see value at current levels. If that bid holds through the volatility spike rather than stepping back, the historical relationship between rate fear and credit stress simply does not fire this cycle. Markets do occasionally decouple from their own history, and a Federal Reserve that has already moved its target range to 3.75 to 4.00 percent with a signal for more tightening gives conviction buyers a clearer floor to defend than they had in prior episodes. Betting on the pattern repeating mechanically, without checking whether the buyer base has changed, is its own kind of error.
What I am watching next is not the spread level itself. It is the flow data behind it: whether redemptions in retail-facing bond funds start accelerating while the volatility gauge stays elevated. That is the tell that turns a lagging indicator into a leading one. A market-neutral volatility book is structured to be indifferent to which gauge turns out to be right, because the position captures the convergence itself rather than a directional call on corporate debt. I am Komey Tetteh, and the question worth asking yourself this week is simple: if you hold corporate credit through a fund structure, do you actually know how liquid your redemption terms are relative to the bonds sitting underneath them, or are you assuming a liquidity that only exists until the moment everyone tries to use it at once.
Common questions
What is the rate market fear gauge
It refers to bond market volatility, a measure of how uncertain traders are about the future direction of yields. It is distinct from credit spreads, which measure the compensation investors demand for corporate default risk. When volatility spikes while spreads stay flat, the two gauges are telling different stories about the same market.
Why haven't corporate bond spreads widened if rate volatility is rising
Corporate credit has stayed resilient through a broader government bond selloff, with investment grade spreads on the original report US Corporate Bond Index sitting around 75 basis points and demand largely absorbing heavy post-Labor Day issuance. Spreads tend to be a lagging signal because they depend on actual sellers showing up, not just on rising uncertainty.
Does rising bond volatility always predict trouble for corporate debt
Historically, spikes in bond market volatility have foreshadowed trouble for corporate debt as nervous retail investors and others pull money from the market. It is a pattern, not a guarantee, and the timing and severity of any repricing has varied across past episodes.
What would break credit markets if this warning proves right
The likely mechanism is retail fund redemptions in less liquid corporate bonds, forcing managers to sell into thin dealer inventory, which widens spreads faster than the underlying default outlook has actually changed. Private credit and CLO structures, which mark more slowly, would likely lag the initial move before showing stress of their own.
What is the counter-argument that this warning is overstated
Heavy corporate issuance since Labor Day has still been absorbed by demand, and spreads have stayed broadly resilient rather than cracking, which suggests real money buyers are still willing to step in at current valuations. If that demand persists through the volatility spike, the historical pattern may simply not repeat this cycle.
How does a delta-neutral volatility strategy respond to this kind of divergence
A market-neutral book positioned across rates and equity volatility does not need to predict which gauge is correct. It is structured to capture the repricing itself, whichever direction it resolves, rather than taking a directional view on corporate bonds or equities.