Ownership was never the variable that moves Petrobras. The pricing formula was, and still is.
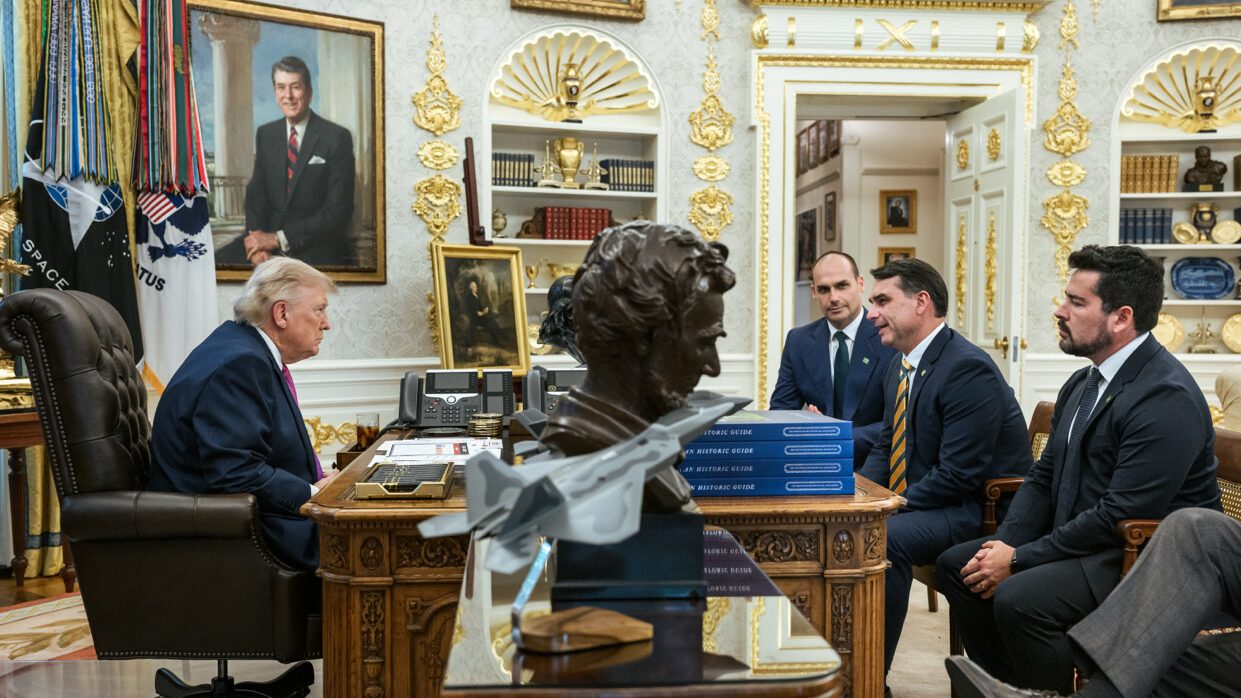
An energy adviser to Flavio Bolsonaro's campaign said that if his candidate wins Brazil's presidential runoff on October 25, Petrobras will not be privatized. The company will instead get broad freedom to restructure its asset portfolio and the government will push to bring more private capital into segments the state oil producer currently dominates. The adviser was explicit: privatization, which Jair Bolsonaro floated during his own presidency, is off the table. The runoff itself is a dead heat, with independent polling putting the two candidates less than two tenths of a percentage point apart.
Read that as a non-event and the mechanism gets missed entirely. Petrobras does not reprice on who owns the shares. It reprices on two things: the formula that sets domestic fuel prices against the international market, and the licensing regime that governs who books the reserves under Brazil's pre-salt fields. Privatization is a headline. Pricing freedom and licensing structure are cash flow.
The transmission channel is the fuel pricing formula, not the share register
Brazil has run a version of import parity pricing since 2016, under which Petrobras adjusts domestic gasoline and diesel prices toward international benchmarks. Every time a sitting president has leaned on that formula to hold prices down for voters, the stock has taken the hit directly, because the market reads intervention as a transfer of value from shareholders to consumers. Petrobras shares fell 21% in a single session in February 2021 after Jair Bolsonaro criticized the company's fuel pricing policy and replaced its market-friendly chief executive. A year later, in a near identical episode, the stock dropped 22% in a day, erasing 71 billion reais in market value, after another round of pricing criticism and another leadership change. Over that period the company burned through three chief executives, each one a proxy fight over the same formula.
That is the channel. A promise to free Petrobras to set prices on its own terms, rather than have a president override the formula ahead of an election, removes the single largest source of single-day tail risk the stock has carried for five years. It has nothing to do with whether the state keeps its controlling stake.
The real asset-level variable is licensing structure, and that is where the second order effect sits
Underneath the pricing question sits a second mechanism that matters more to long-term holders: whether new pre-salt acreage is awarded under production-sharing contracts, which let the state claim a direct share of profit oil and cap investor upside, or under concessions, which let Petrobras and its partners book reserves outright and model cash flow with far more certainty. A shift back toward concession-based rounds, paired with a pricing formula insulated from campaign politics, is a structural change to how the market should value Petrobras reserves on its balance sheet. This is a reserves quality story, not a governance story.
From a delta-neutral volatility book, the way Komey Tetteh frames this is simple: the binary event is the runoff on October 25, but the repricing is not a one-day move. It is a multi-week adjustment in how the forward dividend stream and the reserve base get discounted, and that adjustment runs through the pricing formula and the licensing regime, not the ownership headline.
The honest counter-case
Campaign advisers do not bind presidents. Jair Bolsonaro ran as a market-friendly reformer in 2018 and ended up firing Petrobras chief executives over fuel prices anyway, once the political cost of rising gasoline prices became visible at the pump. A promise of pricing freedom made in October can evaporate the moment diesel prices rise during a cost-of-living fight in year one of a new term. If that happens, the stock reverts to trading on headline political risk again, exactly as it has for most of the last decade, and the licensing framework argument becomes secondary to whichever leader is willing to intervene first.
There is also the arithmetic of the runoff itself. A margin inside the statistical noise of the poll means neither outcome is priced with confidence, and any single-direction position on the pricing formula thesis is a bet on an election that is, by the numbers available, a coin flip.
What we are watching
The signal to track after October 25 is not the ownership statement. It is whether the new administration touches the fuel pricing formula in its first ninety days, and whether licensing rounds for pre-salt blocks move toward concessions or stay under production-sharing terms. Those two data points will tell you more about Petrobras cash flow over the next five years than any privatization headline ever could.
If you are holding Petrobras exposure through the runoff, ask yourself which of those two mechanisms your position is actually priced for, because it is very unlikely to be the one making headlines.
Common questions
Will Petrobras be privatized if Flavio Bolsonaro wins the Brazil election?
No. An energy adviser to Flavio Bolsonaro's campaign stated directly that Petrobras will not be privatized if he wins the October 25 runoff, even though his father Jair Bolsonaro considered privatization while president. The campaign's position is to keep state control while giving the company more freedom over pricing and its portfolio.
Why does Petrobras stock react so strongly to fuel pricing comments from Brazilian presidents?
Petrobras has operated under an import parity pricing formula since 2016 that ties domestic fuel prices to international benchmarks. When presidents publicly pressure the company to hold prices below that formula for political reasons, investors read it as a transfer of value away from shareholders, which has triggered single-day share price drops of over 20% on at least two occasions.
What is the difference between a production-sharing contract and a concession for Petrobras oil fields?
Under a production-sharing contract, the Brazilian state takes a direct share of profit oil once a contractor recovers its costs, which caps investor upside. Under a concession, Petrobras and its partners pay royalties and taxes but can book reserves directly on their own balance sheets, giving clearer long-term cash flow visibility.
How close is the Brazil 2026 presidential runoff between Lula and Flavio Bolsonaro?
Independent polling released in late September 2026 showed Flavio Bolsonaro at 47.7% against Lula's 47.6%, a gap of roughly one tenth of a percentage point that falls within the margin of statistical noise.
Did Jair Bolsonaro ever try to privatize Petrobras?
Yes. In 2022, while president, Jair Bolsonaro authorized his mining and energy minister to study privatizing Petrobras in a potential second term and the company was included in Brazil's Investment Partnerships Program to begin that review, though the privatization never proceeded.
What should investors watch after the Brazil election to gauge the impact on Petrobras?
The two mechanisms that matter are whether the new government intervenes in Petrobras fuel pricing formula in its first months in office, and whether new pre-salt licensing rounds shift toward concession contracts or remain under production-sharing terms. Both affect Petrobras cash flow and reserve accounting far more directly than the ownership question.